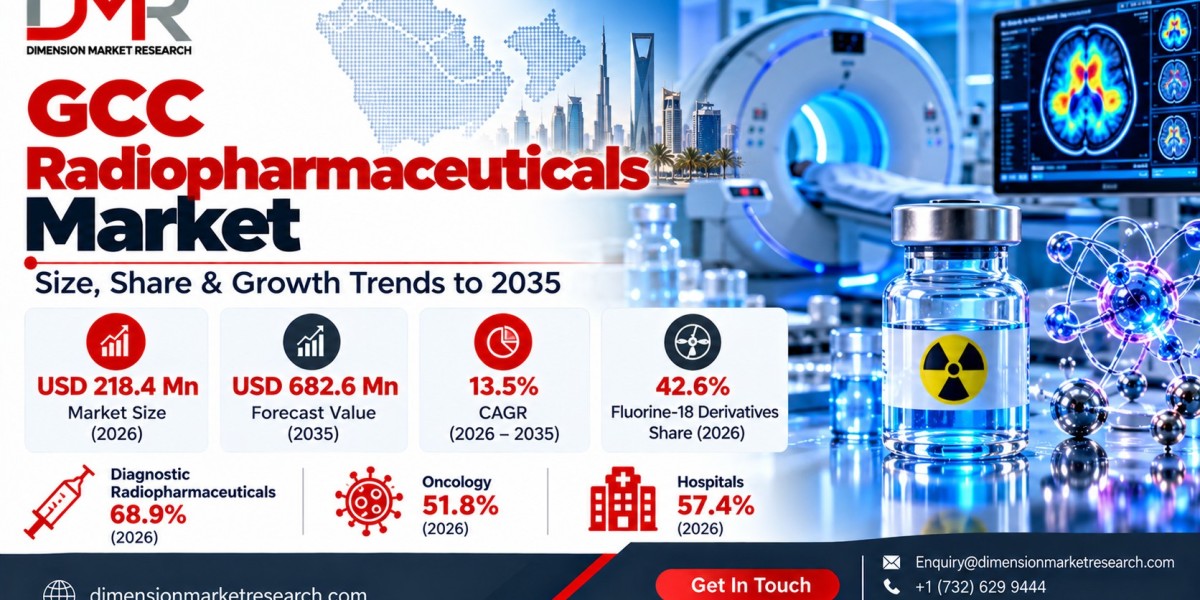

The GCC Radiopharmaceuticals Market is expanding as healthcare systems across the Gulf Cooperation Council invest in advanced cancer diagnostics, nuclear medicine infrastructure, and targeted radiation therapies. According to Dimension Market Research, the market is projected to increase from USD 218.4 million in 2026 to USD 682.6 million by 2035, registering a CAGR of 13.5%.
Government investment in healthcare modernization, expanding PET/CT imaging capabilities, and increasing demand for precision oncology are supporting the adoption of radiopharmaceutical products. Saudi Arabia and the United Arab Emirates are strengthening specialized cancer treatment facilities and regional radioisotope production capabilities.
Growing interest in theranostics, Lutetium-177 radioligand therapy, and Gallium-68 diagnostic imaging is creating opportunities for pharmaceutical manufacturers, nuclear medicine providers, radioisotope suppliers, and healthcare investors.
What Is the GCC Radiopharmaceuticals Market?
The GCC Radiopharmaceuticals Market includes radioactive medicinal products used for diagnostic imaging and targeted treatment across Saudi Arabia, the UAE, Qatar, Kuwait, Oman, and Bahrain.
Radiopharmaceuticals combine pharmaceutical compounds with radioactive isotopes to help healthcare professionals visualize biological processes or deliver radiation to selected disease targets.
Diagnostic products support positron emission tomography (PET) and single-photon emission computed tomography (SPECT).
Therapeutic radiopharmaceuticals deliver targeted radiation for certain cancers and other conditions.
Important radioisotopes include Fluorine-18, Technetium-99m, Gallium-68, Lutetium-177, and Zirconium-89.
Why Is the GCC Radiopharmaceuticals Market Growing?
Government healthcare investment is a major driver. Gulf countries are developing specialized oncology centers, nuclear medicine departments, and advanced diagnostic imaging facilities.
Increasing cancer diagnosis and management requirements are also supporting radiopharmaceutical demand. PET imaging enables clinicians to evaluate tumor activity, cancer staging, and treatment response.
Rising cardiovascular disease burdens create additional opportunities for nuclear cardiology and myocardial perfusion imaging.
Investment in regional cyclotron production can improve access to short-lived radioactive tracers and reduce reliance on international supply chains.
However, high infrastructure costs, radioactive material regulations, isotope transportation challenges, and shortages of specialized personnel remain important barriers.
Get a Free Sample of the GCC Radiopharmaceuticals Market Report
Explore market forecasts, radioisotope segmentation, diagnostic and therapeutic applications, production technologies, country-level opportunities, and competitive intelligence through Dimension Market Research.
The sample can support healthcare investment planning, radiopharmacy expansion, pharmaceutical partnerships, and nuclear medicine technology evaluation.
https://dimensionmarketresearch.com/request-sample/gcc-radiopharmaceuticals-market/
GCC Radiopharmaceuticals Market Size and Key Statistics
● 2026 Market Size: USD 218.4 Million
● 2035 Forecast Revenue: USD 682.6 Million
● Forecast CAGR: 13.5%
● Leading Radioisotope: Fluorine-18 Derivatives, 42.6%
● Leading Type: Diagnostic Radiopharmaceuticals, 68.9%
● Leading Production Source: Cyclotrons, 54.3%
● Leading Application: Oncology, 51.8%
● Leading End User: Hospitals, 57.4%
● Fastest-Growing Radioisotope: Lutetium-177, 17.8% CAGR
● Fastest-Growing Type: Therapeutic Radiopharmaceuticals, 18.4% CAGR
● Fastest-Growing End User: Cancer Research Institutes, 15.2% CAGR
All segment market shares refer to 2026, while segment growth rates cover the 2026–2035 forecast period.
Market Segmentation: Fluorine-18 and Diagnostics Lead
Fluorine-18 derivatives dominate radioisotope segmentation with 42.6% market share in 2026, reflecting their important role in cancer PET imaging.
Fluorine-18 fluorodeoxyglucose, commonly known as FDG, supports cancer detection, staging, and treatment monitoring by measuring metabolic activity.
Diagnostic radiopharmaceuticals account for 68.9% of revenue, supported by established PET and SPECT imaging applications.
Therapeutic radiopharmaceuticals represent a faster-growing category, with a projected 18.4% CAGR, as specialized oncology centers expand access to targeted radioligand therapies.
Cyclotrons lead production sources with 54.3% share, highlighting their role in producing short-lived PET radioisotopes.
Oncology dominates applications with 51.8% share, while hospitals lead end users with 57.4%.
Theranostics and Radioligand Therapy Create New Opportunities
Theranostics is becoming an important development area in nuclear medicine.
This approach combines molecular imaging with targeted treatment, often using related compounds for diagnosis and therapy.
Gallium-68-based radiopharmaceuticals can identify specific disease targets through PET imaging, while selected Lutetium-177 therapies deliver radiation to cells expressing those targets.
These approaches are particularly relevant to certain neuroendocrine tumors and prostate cancers.
Lutetium-177 is expected to register a 17.8% CAGR in the GCC market, supported by expanding therapeutic adoption.
Investment in oncology specialists, radiation safety systems, radioisotope access, and integrated clinical services will be essential for expanding treatment capacity.
How Technology Is Transforming GCC Nuclear Medicine
Advanced PET/CT and PET/MRI systems are improving the ability of nuclear medicine departments to combine molecular and anatomical information.
Digital imaging platforms can support more efficient image processing, clinical workflows, and patient monitoring.
Artificial intelligence offers potential applications in image reconstruction, quality assessment, and selected clinical decision-support tasks, provided systems are appropriately validated.
Radiopharmacy automation can also improve production consistency and reduce unnecessary occupational radiation exposure.
Generator-based radioisotope systems are creating additional opportunities for selected diagnostic applications where cyclotron access is limited.
Together, these technologies can support wider nuclear medicine capabilities across specialized GCC healthcare facilities.
Country Outlook: Saudi Arabia and the UAE Lead Investment
Saudi Arabia is identified as the leading GCC market, supported by expanding hospital infrastructure, oncology services, and nuclear medicine capabilities.
The country's healthcare development initiatives are encouraging investment in PET/CT systems, specialized cancer centers, and domestic radiopharmaceutical distribution.
The United Arab Emirates is another important growth market. Healthcare providers are expanding diagnostic imaging, targeted radionuclide therapies, and specialized nuclear medicine services.
Qatar is developing advanced oncology infrastructure and radiopharmacy capabilities.
Kuwait, Oman, and Bahrain present opportunities through hospital modernization, greater access to diagnostic imaging, and expanding specialized healthcare services.
Regional cooperation in isotope production and distribution could help improve availability across smaller markets.
Competitive Landscape and Strategic Opportunities
Major participants identified in the report include GE HealthCare, Jubilant Radiopharma, Curium Pharma, Lantheus Holdings, Bracco Imaging, Eckert & Ziegler, Nordion, Institute for Radioelements, NTP Radioisotopes, and Telix Pharmaceuticals.
Additional companies include Novartis, Bayer, Siemens Healthineers, ITM Isotope Technologies Munich, SHINE Technologies, and IBA Radiopharma Solutions.
Regional institutions and healthcare providers also play important roles in radiopharmaceutical production, imaging, and treatment delivery.
Competition focuses on isotope availability, production reliability, specialized product portfolios, regulatory compliance, and relationships with hospitals and oncology centers.
Companies investing in local radiopharmacy facilities, theranostic capabilities, and reliable distribution networks may benefit from expanding regional demand.
Future Outlook for the GCC Radiopharmaceuticals Market
Through 2035, the market is expected to benefit from healthcare infrastructure investment, increasing diagnostic imaging demand, and wider adoption of targeted cancer treatments.
Therapeutic radiopharmaceuticals, domestic isotope production, and advanced nuclear medicine services represent important growth opportunities.
Providers combining reliable isotope supply, clinical expertise, regulatory compliance, and specialized oncology partnerships may strengthen their competitive positioning.
Explore the Complete GCC Radiopharmaceuticals Market Analysis
Access the comprehensive Dimension Market Research report for detailed revenue forecasts, isotope segmentation, diagnostic and therapeutic applications, country-level analysis, competitive benchmarking, and investment opportunities across the GCC.
https://dimensionmarketresearch.com/checkout/gcc-radiopharmaceuticals-market/
Frequently Asked Questions
1. What is the GCC Radiopharmaceuticals Market size?
The market is projected to increase from USD 218.4 million in 2026 to USD 682.6 million by 2035.
2. What is the expected CAGR of the GCC Radiopharmaceuticals Market?
The market is forecast to expand at a CAGR of 13.5% between 2026 and 2035.
3. Which radioisotope leads the GCC Radiopharmaceuticals Market?
Fluorine-18 derivatives lead with 42.6% market share in 2026, supported by PET imaging demand.
4. Which application dominates the market?
Oncology dominates with 51.8% share in 2026, reflecting demand for cancer imaging and targeted treatments.
5. Which GCC country leads the Radiopharmaceuticals Market?
Saudi Arabia leads the regional market, supported by investments in advanced healthcare infrastructure and nuclear medicine facilities.
Conclusion
The GCC Radiopharmaceuticals Market is expanding as oncology investment, nuclear medicine modernization, and growing demand for precision diagnostics transform specialized healthcare services.
Fluorine-18 derivatives, diagnostic radiopharmaceuticals, cyclotron production, and hospital applications remain central to demand.
Theranostics, Lutetium-177 therapies, expanded radiopharmacy capacity, and regional isotope production will create significant opportunities through 2035.
Related Radiopharmaceuticals Market Insights
The UK Radiopharmaceuticals Market Size is projected to increase from USD 452.5 million in 2026 to USD 916 million by 2035, registering an 8.2% CAGR. Increasing demand for PET and SPECT imaging, nuclear medicine services, and targeted radioligand therapies supports growth. Diagnostic radiopharmaceuticals lead with 62% market share in 2026, while oncology accounts for 47% of application demand.
The India Radiopharmaceuticals Market Share reflects expanding nuclear medicine infrastructure, domestic isotope production, and precision oncology adoption. The market is projected to increase from USD 524.0 million in 2026 to USD 1,060.0 million by 2035, registering an 8.2% CAGR. Diagnostic radiopharmaceuticals account for 68.4% share, while hospitals lead end users with 62.7% in 2026.
The Japan Radiopharmaceuticals Market Growth is supported by advanced nuclear medicine infrastructure, an aging population, and investment in targeted radioligand therapies. The market is projected to grow from USD 1.6 billion in 2026 to USD 3.9 billion by 2035, registering a 9.9% CAGR. Diagnostic products lead with 61.4% share, while oncology accounts for 48.6% of application demand in 2026.